How to Save Money Buying a House in Utah: The 2026 Insider Guide

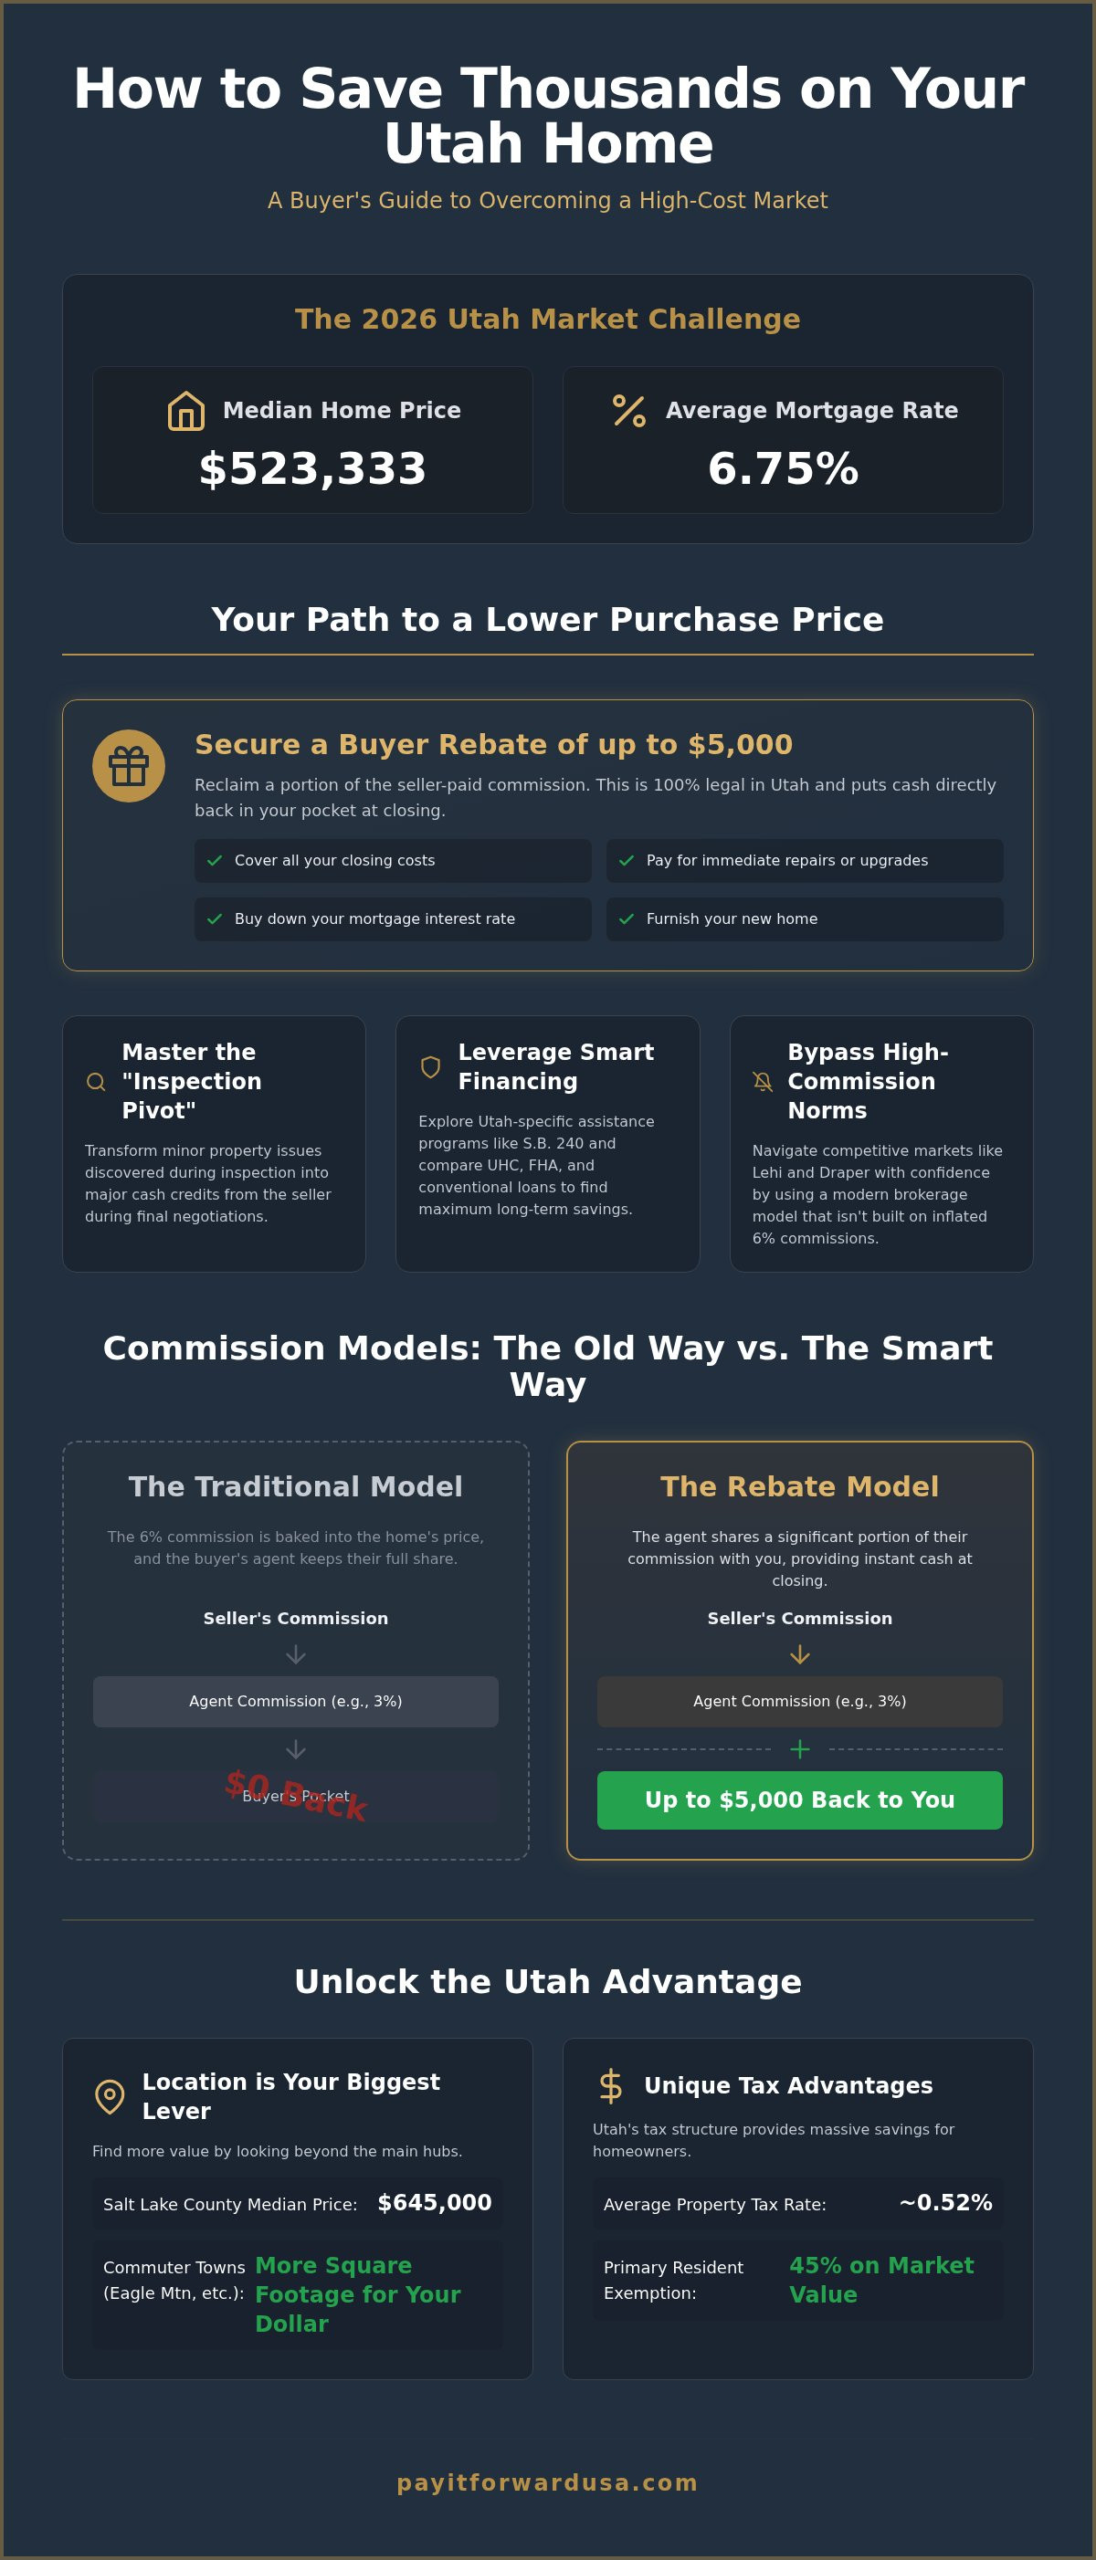
The biggest savings in Utah real estate don’t come from your bank; they come from reclaiming the commission the seller is already paying. With the median home price sitting at $523,333 and mortgage rates at 6.75%, mastering how to save money buying a house in utah is a survival skill. You have likely felt the sting of bidding wars in Lehi or the budget-crushing reality of high monthly payments. It is exhausting to watch your dream home slip away because of a 20% down payment requirement you haven’t met yet.
We understand that the current market feels stacked against you. That is why we are showing you exactly how to flip the script. This guide reveals “hidden” strategies and a buyer rebate of up to $5,000 that puts cash back in your pocket at closing for repairs or new furniture. We will explore local grants like the S.B. 240 program and show you how to handle the 2026 market without being bullied by high-commission agents. Get ready to lower your effective purchase price and take control of your financial future.
Key Takeaways
- Secure a buyer rebate of up to $5,000 at closing to wipe out your initial home expenses or cover immediate upgrades.
- Master the “Inspection Pivot” to transform minor property issues into major cash credits during the final negotiation phase.
- Discover the exact formula for how to save money buying a house in utah by leveraging the latest 2026 state and local assistance programs.
- Stop overpaying for your mortgage by comparing UHC, FHA, and conventional loans side-by-side for maximum long-term savings.
- Navigate competitive markets like Lehi and Draper with confidence using insider strategies that bypass high-commission industry norms.
Understanding the True Cost of Utah Real Estate in 2026
Utah’s housing market in 2026 is a complex balancing act. Sellers are clinging to high valuations while buyers are squeezed by 6.75% mortgage rates. This dynamic creates “sticky” prices that don’t drop as fast as buyers hope. You might see a $540,000 listing on Zillow and think that is your budget. It isn’t. The sticker price is just the starting line. Beyond the mortgage, you must account for inspections, appraisals, and title fees that can add thousands to your closing day. If you are looking at growing communities like Herriman or Daybreak, local HOA fees can quietly add $200 to $500 to your monthly overhead. Learning how to save money buying a house in utah starts with seeing these invisible drains on your bank account before you sign.
The Salt Lake and Utah County Price Divide
Location is your biggest lever for savings. In Salt Lake County, the median price hit $645,000 in early 2026. Compare that to the tech corridor in Lehi where bidding wars still erupt. If you want more square footage for your dollar, look toward commuter towns like Eagle Mountain or South Jordan. You also benefit from a unique “Utah Tax” advantage. Our average effective property tax rate is roughly 0.52%. Even better, primary residents get a 45% exemption on their home’s market value. This is a massive financial win compared to the tax burdens in neighboring states. Choosing the right zip code is the first step in how to save money buying a house in utah.
Why Traditional Real Estate Models Cost You Money
Most buyers think their agent is free. That is a myth that costs you. The traditional 6% commission is baked directly into the home’s sales price. If that commission didn’t exist, the house could technically cost less. By understanding the mechanics of Buyer Brokerage, you can see how the system is often rigged to keep prices high. Commission-sharing in Utah allows a buyer’s broker to receive a portion of the seller-paid commission and then legally rebate a significant chunk of it back to you at closing. This strategy pulls back the curtain on industry norms and puts the power back in your hands. It is a modern, scrappy way to ensure you aren’t overpaying for the privilege of owning a home.
The Buyer Rebate: How to Get Up to $5,000 Back at Closing
Most real estate agents treat their commission like a state secret. They don’t want you to know that the commission paid by the seller can actually work in your favor. In Utah, commission rebates are 100% legal. This is one of the most effective ways for how to save money buying a house in utah, yet it remains largely ignored by traditional big-box firms. A buyer rebate is essentially a portion of the agent’s commission that is handed back to you at the closing table. Instead of your agent pocketing the entire fee, they share the wealth to help you cross the finish line.
The mechanics are straightforward. When you work with Pay It Forward Realty LLC, we collect the commission offered by the seller and credit up to $5,000 of it directly to you. This isn’t just a discount; it’s a strategic tool. You can use that cash to cover your closing costs, which often catch buyers by surprise. Alternatively, you can use it to buy down your interest rate. With fixed rates remaining a primary concern for local buyers, a permanent rate buy-down can save you tens of thousands of dollars over the life of your loan. A $5,000 rebate changes your move-in day from a financial drain into a win. It covers the new fridge, the professional deep clean, or the unexpected repairs that always seem to pop up in the first month.
Qualifying for Your Utah Home Buyer Rebate
To secure this benefit, you must be proactive. You can’t ask for a rebate after you have already signed a standard, high-commission buyer’s agreement. You need to choose a rebate-friendly broker before you start touring homes in areas like Draper or Eagle Mountain. Documentation is key. Your rebate must be clearly listed on the Settlement Statement (the ALTA) to ensure full transparency with your lender. For a step-by-step breakdown of the process, check out our Utah Home Buyer Rebate Guide 2026: Get Up to $5, 000 Cash Back. Following these specific Utah Housing Market Research trends shows that savvy buyers are increasingly moving away from traditional models to keep more of their equity.
Rebate vs. Price Reduction: Which is Better?
Many buyers wonder if they should just ask for a lower purchase price instead. While a lower price reduces your mortgage balance, a rebate provides immediate liquidity. Cash at closing is often more valuable because it preserves your savings. Lenders generally prefer rebates when they are applied toward closing costs because it strengthens your financial position at the start of the loan. If you want to maximize your “Cash to Close” efficiency, a rebate is the undisputed champion. It allows you to keep your hard-earned money in your bank account while still securing the home you want. If you are ready to see how this works in practice, you can explore our available buyer packages to find the right fit for your journey.
Smart Financing: Leveraging Utah Down Payment Assistance
Interest rates of 6.75% can feel like a barrier, but your financing strategy is your best weapon. You don’t need a massive 20% down payment to get the keys. In fact, doing so might drain your liquidity when you need it most. The 2026 market for Utah Housing Corporation down payment assistance offers a second mortgage of up to 6% of your first mortgage amount. This helps you bridge the gap without emptying your savings. By partnering with a local expert like True North Mortgage for a free prequalification, you gain a clear view of your buying power before you step into a single open house. This is a critical step in how to save money buying a house in utah because it prevents you from falling in love with a home that doesn’t fit your long-term financial health.
Combining these state programs with our buyer rebate of up to $5,000 creates a “Zero-Down” feel that traditional agents rarely mention. While FHA loans offer a low 3.5% down payment, they carry permanent mortgage insurance. Conventional loans might have slightly higher rates but allow you to drop PMI once you hit 20% equity. For our veterans, VA loans remain the gold standard with $0 down and no monthly insurance. Choosing the right loan type isn’t just about the rate; it’s about the total cost over the first five years of ownership.
Utah-Specific Assistance Programs to Watch
Specific grants can drastically lower your entry cost. The S.B. 240 program provides up to $20,000 for new construction homes priced at or below $450,000. If you are looking in Salt Lake County, the FHLB HELP program offers a forgivable grant of up to $20,000 after five years of residency. Neighbor Works programs in Murray even offer up to $85,000 in no-interest, forgivable loans for those who qualify. These are not just “first-timer” perks; they are strategic financial moves for anyone wondering how to save money buying a house in utah.
Mortgage Hacks to Lower Your Monthly Payment
Don’t let high rates dictate your lifestyle. Use the “2-1 Buydown” strategy. This allows you to pay a lower interest rate for the first two years of your loan, giving you breathing room while you wait for a future refinance. Your credit score also plays a massive role in your Private Mortgage Insurance (PMI) costs. A higher score can slash your monthly insurance premium by half. Finally, check local Utah credit unions. They often have more flexible debt-to-income requirements than national banks, giving you an edge in a tight market.
Hidden Negotiation Strategies to Slash Your Closing Costs
Negotiation is where savvy buyers separate themselves from the crowd. It is not just about the final sales price; it is about the terms that dictate your out-of-pocket expenses. In a balanced 2026 market where the average discount from list price is roughly 2% to 3%, you have room to breathe. Understanding how to save money buying a house in utah means looking past the granite countertops and focusing on the settlement statement. Sellers in areas like Bountiful are often more motivated in December when inventory sits longer. With a median of 54 days on the market, time is your greatest ally. Use it to push for terms that keep your cash in your pocket.
The “Inspection Pivot” is a high-impact move for any buyer. When the inspection report reveals a $2,000 electrical issue, don’t just ask the seller to fix it. Repairs done by sellers are often the cheapest possible solution. Instead, ask for a $2,500 cash credit toward your closing costs. This increases your liquidity and allows you to oversee the quality of the repair after you move in. You should also negotiate your Buyer Agency Agreement for maximum flexibility. Don’t get locked into a rigid, high-commission contract that prevents you from claiming a rebate.
The Art of the Seller-Paid Closing Cost
In competitive hubs like Lehi, you might feel hesitant to ask for favors. However, structuring an offer with “Seller Concessions” is a standard practice that can save you thousands. By asking for 3% back at closing, you effectively roll your transaction fees into the mortgage. This preserves your cash for immediate needs like new flooring or furniture. To win this negotiation, you must understand the other side of the table. Review our guide on How Much Does It Cost to Sell a House in Utah FSBO? The 2026 Cost Breakdown to see exactly how much margin a seller has to work with. When you know their costs, you know exactly how hard you can push.
Avoiding “Junk Fees” at the Title Company
The title company is often the final hurdle where “junk fees” can creep into your budget. Always review your Loan Estimate (LE) with a critical eye. Look for vague charges like “administrative fees” or “document preparation” that can add $500 to your bill. Utah has a competitive title industry; you aren’t required to use the seller’s preferred provider. Challenge these fees before you sign the final papers. Combining a clean title bill with our up to $5,000 rebate ensures you aren’t leaving a single dollar on the table. If you want a partner who fights for every cent, start your journey with Pay It Forward Realty today.
The Pay It Forward Strategy: Your Path to a Lower Purchase Price
Traditional real estate agents often talk about “service” while staying silent about the massive commission checks they pocket at your expense. We do things differently. Pay It Forward Realty LLC is the savvy choice for buyers who want to strip away the industry fluff and focus on the bottom line. By combining an up to $5,000 rebate with expert local advocacy, we effectively lower your purchase price before you even move in. This is the smartest way for how to save money buying a house in utah in 2026. Our “Full Transparency” promise means you see exactly where every dollar goes. No hidden fees. No surprise costs. Just a clear path to homeownership that respects your bank account.
Getting started is simple and risk-free. We partner with True North Mortgage to provide free, no-obligation prequalifications. This gives you the confidence to make aggressive offers in a market where the median home price remains sticky at $523,333. When you know your numbers and have an up to $5,000 rebate in your back pocket, you aren’t just another buyer; you are a savvy investor in your own future. We act as your bold ally, ensuring you navigate the Wasatch Front market without the burden of high-commission industry norms that have historically favored the broker over the consumer.
A Local Ally in the Wasatch Front
We don’t just work in Utah; we live here. Our expertise spans from the tech hubs of Saratoga Springs to the growing communities in Herriman and beyond. Principal Broker Kurt Mathewson built this model on a foundation of consumer advocacy. He believes that the traditional 6% commission model is outdated and unfair to modern buyers who do much of their own research online. By choosing a local expert who understands the specific nuances of Utah County and Salt Lake County, you gain an edge in every negotiation. For a deeper look at how we are changing the game, explore our Ultimate Guide to Low Commission Real Estate in Utah: Save Your Equity in 2026. We are committed to helping you keep more of your hard-earned equity.
Your 30-Day Action Plan to Homeownership
Ready to stop dreaming and start signing? Follow this streamlined path to find your perfect home while maximizing your savings. This is the definitive blueprint for how to save money buying a house in utah.
- Step 1: Get prequalified at no cost or obligation. Knowledge is power. Use our partnership with True North Mortgage to lock in your budget early and prove to sellers you are a serious contender.
- Step 2: Sign a rebate-eligible buyer agreement. Secure your up to $5,000 advantage right from the start. We put our commitment to your savings in writing so there is no confusion at the closing table.
- Step 3: Hunt for your Utah dream home with a $5,000 advantage. Tour homes in Eagle Mountain, South Jordan, or Draper knowing you have extra cash waiting for you to cover closing costs or immediate upgrades.
Don’t let traditional commission structures drain your savings. Take control of your real estate journey today. Get your free mortgage prequalification and start saving today!
Take Control of Your Utah Home Purchase Today
You don’t have to settle for the high costs of the traditional real estate machine. Mastering how to save money buying a house in utah is about using every tool available; from state assistance programs to the powerful “Inspection Pivot.” By reclaiming the commission the seller is already paying, you can walk away from the closing table with up to $5,000 in your pocket. This isn’t just a discount. It’s your furniture fund, your repair budget, or your interest rate buy-down.
You deserve a licensed Utah Principal Broker who prioritizes your equity over their own commission. We make it simple to start with a free mortgage prequalification via True North Mortgage. This transparency ensures you know your buying power before you ever step foot in a Saratoga Springs or Herriman open house. Stop leaving your hard-earned money on the table and start your journey with a bold ally in your corner.
Start your Utah home search and claim your $5, 000 rebate here!
The 2026 market is waiting, and now you have the insider edge to win it on your own terms.
Frequently Asked Questions
Can I really get a cash rebate when buying a house in Utah?
Yes, you can legally receive a cash rebate at the closing table. This is one of the most effective strategies for how to save money buying a house in utah. The rebate is a portion of the commission the seller pays to the buyer agent. Instead of the broker pocketing the full amount, they share it with you to help cover your transaction costs or immediate home upgrades.
How much can I save with a Utah home buyer rebate?
You can save up to $5,000 depending on the purchase price and the commission offered by the seller. This cash is credited to you at the end of the transaction. It effectively lowers your move-in costs, allowing you to keep more of your savings for things like new appliances or essential repairs. It is a significant financial win in a market with high sticky prices.
Is a buyer rebate legal according to the Utah Division of Real Estate?
Yes, buyer rebates are fully legal in the state of Utah. The Utah Division of Real Estate allows licensed agents to share their commission with the parties involved in the transaction. To stay compliant, the rebate must be clearly documented on the settlement statement. This ensures full transparency for all parties, including your lender, and protects your financial interests throughout the entire escrow process.
What happens if the seller refuses to pay a buyer agent commission?
If a seller refuses to pay the commission, the responsibility for the agent fee typically falls on the buyer. This has become a more frequent reality in the 2026 market. In these cases, you should negotiate the agent fee upfront. Choosing a broker with a transparent, low-cost structure ensures you aren’t hit with unexpected high-commission bills when the seller isn’t footing the bill.
Can I use my buyer rebate to cover my down payment?
No, you typically cannot use a rebate for your minimum down payment requirement. Lenders generally require the down payment to come from your verified personal funds. However, the rebate is excellent for covering closing costs or buying down your interest rate. By using the rebate for these expenses, you free up more of your own cash to meet the lender’s specific down payment requirements.
How do I find a realtor in Utah who offers commission rebates?
You should search for consumer-advocacy brokers who prioritize transparency over traditional high commissions. Pay It Forward Realty LLC is a prime example of a local Utah firm that puts money back in your pocket. Always ask for a written agreement that explicitly mentions the rebate before you start touring homes. This ensures you are legally entitled to your up to $5,000 credit at closing.
What are the income limits for Utah down payment assistance in 2026?
Income limits for 2026 vary significantly based on the specific county and your household size. For many Utah Housing Corporation programs, the limits are designed to help moderate-income families. You should always check the latest UHC charts for Salt Lake or Utah County. Getting a free prequalification through a partner like True North Mortgage is the fastest way to see which assistance programs fit your specific income level.
What is the best month to buy a house in Utah to save money?
December is historically the best month to find the deepest discounts in Utah. With a median of 54 days on the market, winter sellers are often highly motivated to close before the new year. Buying during the off-season is a pro tip for how to save money buying a house in utah because there is less competition, giving you more leverage to negotiate significant seller concessions.