Salt Lake City Home Buyer Incentives 2026: The Ultimate Savings Guide

Most home buyers in Utah leave $20,000 on the table because they don’t know which doors to knock on. It’s exhausting to watch Salt Lake City prices jump 13 percent in a year while you’re still scraping for a down payment. You deserve a win. Finding the right salt lake city home buyer incentives shouldn’t feel like a lottery. It’s your secret weapon to lower your cash-to-close and beat the competition. Let’s get savvy.
We’re pulling back the curtain on every grant, loan, and rebate available in 2026. This guide isn’t a list of programs with full waitlists; it’s a roadmap to real savings. You’ll discover how to stack $20,000 state assistance for new builds with local forgivable loans. We’ll also explain how a $5,000 buyer rebate puts money back in your pocket at the closing table. Stop letting complex eligibility rules and high costs hold you back. It’s time to act like a savvy insider and finally secure your piece of the Wasatch Front.
Key Takeaways
- Identify the strict eligibility rules for the $20,000 state grant and the $10,000 city-specific assistance programs available right now.
- Learn how to stack various salt lake city home buyer incentives, including lender credits and seller-paid costs, to slash your cash-to-close.
- Secure a guaranteed buyer rebate of up to $5,000 by partnering with a brokerage that shares its commission with you.
- Follow a concrete 30-day checklist to prequalify for funding and beat the competition in Salt Lake’s most popular neighborhoods.
Navigating the Salt Lake City Home Buyer Incentive Landscape in 2026
The 2026 market is a paradox. While home prices in Salt Lake City surged to a median of $586,250 as of March, the frenetic bidding wars of previous years have shifted toward a more stabilized yet inventory-starved environment. This makes 2026 a critical window. If you wait, you risk being priced out. If you act without a plan, you leave money on the table. Understanding the full spectrum of salt lake city home buyer incentives is the only way to bridge the gap between “I’m looking” and “I’m moving in.” These incentives aren’t just safety nets; they’re high-octane financial tools including grants, tax credits, and commission rebates.
Whether you’re hunting in the urban core of Salt Lake City, the quiet streets of Murray, or the expanding neighborhoods of West Valley, your strategy must change based on your zip code. Most buyers only look at government grants. That’s a mistake. While state programs offer massive boosts, private brokerage incentives provide a level of reliability that government lotteries can’t match. You need a mix of both to win in this market.
The Difference Between Grants, Loans, and Rebates
Not all “assistance” is created equal. You need to know exactly what you’re signing up for before you reach the closing table. Each has a different impact on your long-term wealth.
- Grants: This is essentially “free money.” Most grants, like the American Dream Grant, don’t require repayment as long as you live in the home for a specific period. They’re perfect for a first-time home buyer looking to lower their initial investment.
- Deferred Loans: These are zero-interest second mortgages. You don’t make monthly payments, but you’ll repay the balance when you sell or refinance the home. These are common in state-level programs.
- Buyer Rebates: This is the most underrated tool. It’s a legal share of the real estate commission given back to you. While traditional agents pocket the whole check, savvy brokers share it to help you cover closing costs.
Why Salt Lake City is a Unique Market for Incentives
Salt Lake City isn’t just another metro area; it’s a patchwork of specific municipal rules. Local programs often have tighter boundaries than statewide Utah Housing Corporation initiatives. For instance, some city-specific forgivable loans are only available within certain city limits, while the $20,000 state grant is tied strictly to new construction under $450,000. Inventory levels across the Wasatch Front dictate which salt lake city home buyer incentives you can actually trigger. Pairing these with a low commission real estate utah strategy ensures you aren’t just saving on the purchase, but protecting your equity from day one.
State and Local Government Programs: Grants and Down Payment Assistance
Government programs are the heavy hitters of salt lake city home buyer incentives. They offer massive relief, but they come with strings attached. You can’t just walk in and claim a check. You need to understand the math behind Area Median Income (AMI). Most programs cap eligibility at 80 percent of the local AMI, though some go higher. If you haven’t owned a home in the last three years, you’re usually in the clear. This is where savvy buyers separate themselves from the crowd by knowing which rules apply to their specific situation.
The Utah $20,000 First-Time Homebuyer Grant
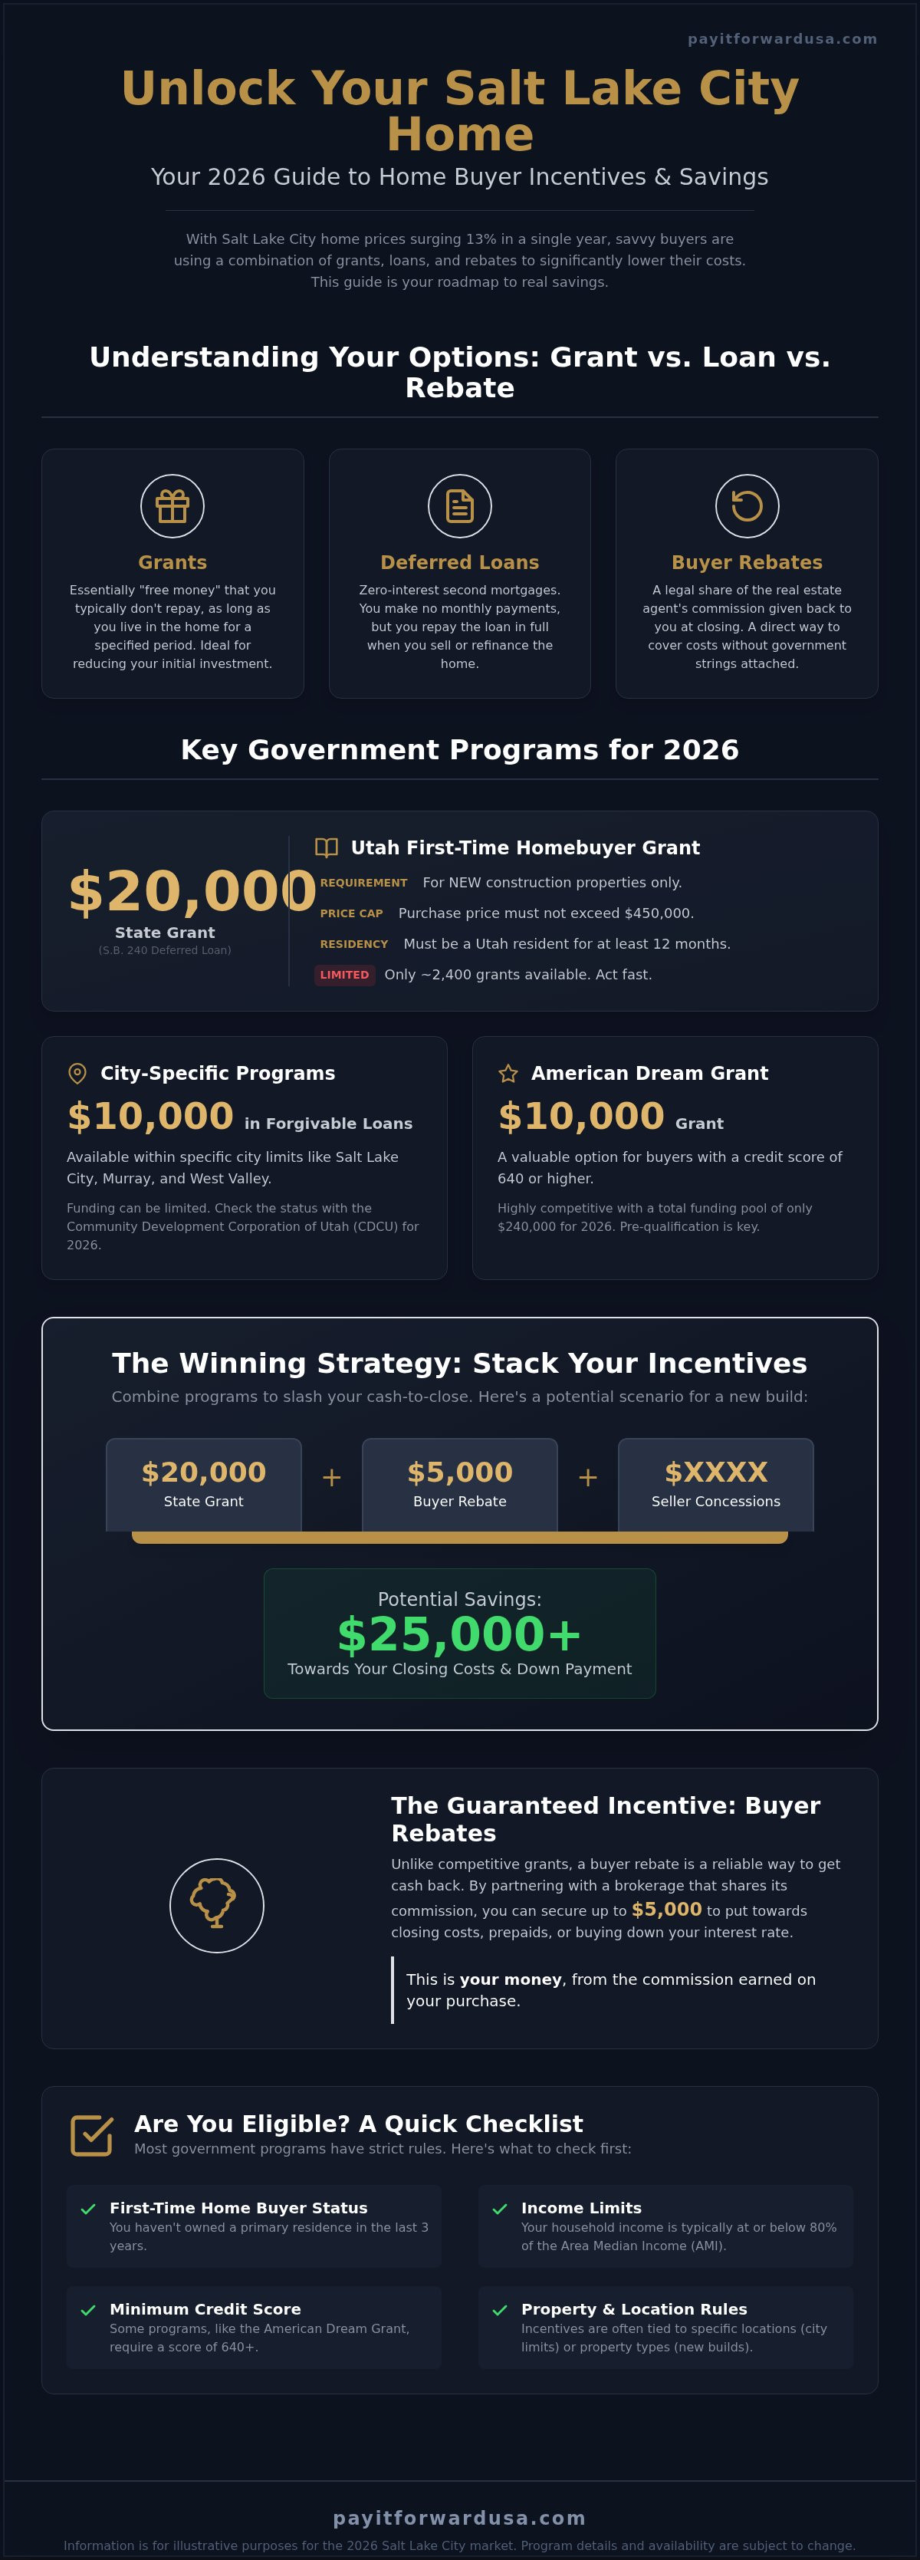
This is the big one. Senate Bill 240 created a $20,000 deferred loan for buyers looking at new construction. It’s a game changer if you want a fresh build, but the purchase price cannot exceed $450,000. You also need to be a Utah resident for at least 12 months. This isn’t a permanent gift; you’ll repay it when you sell the home or refinance. With a limit of 2,400 qualifying buyers, the clock is ticking. Get your mortgage prequalification sorted early so you’re ready to strike before the 2026 budget runs dry.
City-Specific Programs: Murray, Midvale, and West Valley
Don’t overlook municipal funds. Salt Lake City offers up to $10,000 in forgivable loans within city limits. Murray and West Valley often have their own pots of money managed through the Community Development Corporation of Utah (CDCU). Keep in mind that CDCU funding can be hit or miss. They didn’t receive funds in 2023, so checking their 2026 status is mandatory. These programs often target urban renewal. This means you might get extra help for buying in specific neighborhoods that the city wants to revitalize. It’s a localized strategy that requires a bit of legwork but pays off at the closing table.
The American Dream Grant is another $10,000 option. With $240,000 total available for 2026, it’s a tight window. It’s available for those with a credit score higher than 640 and a household income under $141,400. You must close within 90 days of being awarded the grant. Because these funds are first-come, first-served, they often feel like a race. Contrast this with private rebates that don’t run out of money. Winning in 2026 requires knowing which bucket to pull from at exactly the right time.
The Guaranteed Incentive: Utah Home Buyer Rebates Explained
Government grants are great, but they are often a lottery. What if you make slightly too much money for the AMI limits discussed earlier? What if the state fund runs out in July? This is where the most reliable of all salt lake city home buyer incentives comes into play: the commission rebate. In Utah, it’s perfectly legal for a broker to share their commission with the buyer. While other shoppers wait for government approval or budget cycles, savvy buyers use rebates to create their own financial advantage.
Pay It Forward Realty LLC provides a buyer rebate of up to $5,000. Unlike government programs, there are no income restrictions. You don’t have to be a first-time buyer to qualify. It’s a transparent, no-nonsense way to lower your out-of-pocket costs at the closing table. It acts as a guaranteed win in a market that often feels unpredictable.
How the $5,000 Buyer Rebate Works
The mechanics are straightforward. When a seller lists a home, they typically agree to pay a commission to the buyer’s agent. Instead of pocketing that entire check, we share our portion with you. It’s your transaction, and we believe you should keep more of your hard-earned equity. You can apply this Utah home buyer rebate directly to your closing costs, use it for a mortgage rate buy-down, or even negotiate a price reduction.
Think about the immediate impact. A $5,000 credit on your Closing Disclosure means $5,000 less cash you need to bring to the bank on move-in day. It’s a tangible result that doesn’t depend on a city council’s next budget meeting or a specific neighborhood’s renewal status. It’s about giving you the autonomy to manage your own high-stakes transaction.
Rebates vs. Traditional Agents
Most traditional agents keep the full 2.5 or 3 percent commission for themselves. They often argue that their “prestige” or “full-service” model justifies the high cost. We see it differently. In 2026, buyers are more informed than ever before. You are doing the research. You are tracking the SLC neighborhoods on your phone daily. Why should you pay for a corporate model that hasn’t changed in decades?
Pay It Forward Realty LLC acts as your bold ally. We handle the professional negotiations, the legal contracts, and the complex paperwork, but we reward your autonomy with cash back. To ensure everything is perfectly legal and documented, we record the rebate on your settlement statement. This transparency removes the unnecessary barriers that traditional real estate norms try to keep in place. If you want salt lake city home buyer incentives that are actually within your control and guaranteed to exist when you find your dream home, the commission rebate is the only logical choice.
Strategic Stacking: How to Maximize Your Buyer Incentives in SLC
Finding a single grant is a win. Stacking three or four different salt lake city home buyer incentives is a masterclass in financial intelligence. This is the “Savvy Buyer Stack.” In the 2026 market, don’t just settle for one source of savings. Layer state-level grants with private rebates, lender credits, and seller concessions. When you combine these tools, you don’t just lower your monthly payment. You drastically reduce the actual cash you need to bring to the closing table. Play the game at a higher level.
Timing is everything. Many government funds operate on fiscal cycles, often replenishing in the spring or summer. If you align your search with these cycles, you’re more likely to catch the full $20,000 state grant before the 2,400-buyer limit is reached. But even if the state funds are dry, your private rebate and seller-paid costs remain on the table. You’re never without options if you know how to layer them correctly.
Step 1: Get Prequalified and Identify Your Baseline
Stop guessing what you can afford. Start with a solid foundation. We partner with True North Mortgage to provide free mortgage prequalification with no obligation. This isn’t just a piece of paper; it’s the gatekeeper for the most lucrative salt lake city home buyer incentives. You cannot even apply for the $20,000 state assistance program without an approved lender in your corner from day one. Understanding your maximum loan-to-value (LTV) ratio helps you see exactly where an incentive can fill the gap between your savings and the bank’s requirements. Get your numbers right first.
Step 2: Layering the Buyer Rebate with Seller Concessions
This is where the real magic happens. Even in a competitive market, motivated sellers are often willing to pay for your closing costs or a 2/1 rate buy-down to get the deal done. Use the utah mls listing service to identify properties that have been sitting for more than 30 days. These sellers are your primary targets for concessions. Imagine getting the seller to pay $10,000 toward your interest rate while you still pocket your $5,000 buyer rebate. That’s a $15,000 swing in your favor. When writing your offer, use specific language that protects these credits. Ensure your rebate is clearly disclosed so the lender can apply it toward your non-recurring closing costs without a hitch.
Ready to build your own savings stack? Talk to a local expert today to see how much you can save at closing.
Your Next Steps: Claiming Your Salt Lake City Incentives
You have the data and the strategy. Now you need the execution. Don’t let the 2026 market pass you by while you’re still doing math on the sidelines. The window for the most lucrative salt lake city home buyer incentives can close fast as state budgets are depleted. It’s time to move from research to results. Follow this 30-day action checklist to secure your spot at the closing table with thousands in savings.
- Day 1: Get prequalified with True North Mortgage to establish your baseline and loan-to-value limits.
- Day 7: Verify your 2026 AMI eligibility for city-specific grants in Murray, West Valley, or Sandy.
- Day 10: Interview buyer agents and secure a written rebate agreement to lock in your savings.
- Day 14: Map out your “Savings Stack” by identifying new construction for the $20,000 state grant.
- Day 21: Begin active house hunting with a pre-approved offer strategy that accounts for seller concessions.
Choosing a brokerage that understands the entire ecosystem gives you a massive competitive advantage. At Pay It Forward Realty LLC, we don’t just help you buy. We understand the mechanics of flat fee mls utah and buyer rebates because we believe in transparency over tradition. We are your bold ally. We strip away the corporate stiffness to ensure you keep your hard-earned equity. Don’t leave $5,000 on the table just because a traditional agent wants to keep the status quo alive.
Interviewing Your Buyer Agent About Rebates
Not every agent is an ally. When you start your search, ask one simple question: “Do you offer a written rebate agreement?” If they hesitate or claim that rebates are illegal, walk away. Rebates are 100 percent legal in Utah. Some agents use these myths to protect their high commissions. Pay It Forward Realty LLC simplifies the paperwork and ensures your salt lake city home buyer incentives are documented clearly on your settlement statement. It’s your money. You deserve to see it at closing.
Get Your Free Prequalification Today
Knowledge is power, but data is the fuel for your home search. Our partnership with True North Mortgage gives you access to free mortgage prequalification with no obligation. This is the first and most vital step to unlocking state and city grants. It’s fast. It’s simple. It’s the only way to prove to sellers that you’re a savvy, serious buyer. Stop guessing and start planning. Contact Kurt Mathewson at Pay It Forward Realty LLC today to start your savvy home search and claim the savings you deserve.
Claim Your Savings and Secure Your Future
The 2026 market doesn’t wait for the unprepared. You’ve seen the numbers. You know that while government grants provide a massive boost, they are often first-come, first-served lotteries. Relying on a lottery isn’t a strategy; it’s a gamble. By understanding how to stack salt lake city home buyer incentives, you move from being a spectator to a savvy homeowner. You now have the roadmap to layer $20,000 grants with guaranteed commission rebates and seller concessions. It’s time to act.
Pay It Forward Realty LLC is your bold ally. We don’t believe in the old-school model where agents keep everything for themselves. We provide an expert local brokerage experience with the transparency you deserve. Why settle for less when you can get a free mortgage prequalification and up to $5,000 cash back at the closing table? It’s your equity. It’s your home. Let’s make it happen.
Get Your $5,000 Buyer Rebate – Start Here
Your dream home along the Wasatch Front is within reach. Don’t let complex rules or high costs stop you. Take the first step today and watch how fast your savings add up.
Frequently Asked Questions
Are home buyer rebates legal in Utah?
Yes, real estate commission rebates are 100 percent legal in Utah. The IRS treats these funds as a reduction in the home’s cost basis rather than taxable income. While some traditional agents might claim otherwise to protect their high commissions, Utah law clearly allows brokers to share their earnings with you. It is a powerful, guaranteed way to lower your closing costs without needing to wait for government approval or budget cycles.
Can I use the $20,000 Utah first-time homebuyer grant on any house?
No, the Utah First-Time Homebuyer Assistance Program is strictly for new construction homes. The property must have been built in 2023 or later and never occupied. Additionally, the purchase price cannot exceed $450,000. It is a specific tool meant to encourage new housing development. If you are looking at existing homes, you should explore city-specific grants or commission rebates instead to find the best possible savings.
What is the income limit for Salt Lake City down payment assistance?
For the American Dream Grant in 2026, your household income must be no more than $141,400. Other programs within Salt Lake City limits often use 80 percent of the Area Median Income (AMI) as a ceiling for eligibility. These limits change annually based on federal data and household size. It is vital to verify your current income against the specific program’s 2026 guidelines before you start the application process.
Do I have to pay back the $5,000 rebate from Pay It Forward Realty?
No, you never have to pay back a buyer rebate. Unlike deferred loans or forgivable grants that have strict residency requirements, a commission rebate is simply your share of the agent’s earnings. It is credited to you at the closing table to reduce your out-of-pocket expenses. Once the deal is done, that money is yours to keep. It acts as a permanent reduction in the total cost of your home.
Can I stack a seller credit with a buyer rebate?
Yes, you can absolutely stack a seller credit with a buyer rebate. In fact, layering these salt lake city home buyer incentives is a pro move for savvy buyers. You might negotiate a $10,000 seller credit for a rate buy-down and then add your $5,000 rebate to cover remaining closing costs. This strategy maximizes your total savings and keeps more cash in your bank account on move-in day.
What is the difference between a grant and a deferred loan in SLC?
A grant is typically “free money” that is forgiven after you live in the home for a set period, like five years. A deferred loan is a zero-interest second mortgage that must be repaid eventually. Usually, you pay the deferred loan back when you sell the property or refinance your primary mortgage. Both help you get into a home, but the long-term repayment terms and financial obligations are very different.
How long does it take to get approved for Utah DPA programs?
Approval times vary, but you should expect the process to take 30 to 45 days on average. Most programs require you to complete a homebuyer education course and secure a mortgage prequalification first. Because many salt lake city home buyer incentives are funded on a first-come, first-served basis, you need to have your paperwork ready to go the moment you find a qualifying home. Speed is your biggest advantage.
Is there a limit on the purchase price for SLC buyer incentives?
Yes, price caps are common. For the $20,000 state grant, the limit is $450,000. However, for conventional loans in Salt Lake City in 2026, the conforming limit for a single unit is $806,500. FHA limits are lower at $524,250 for a single-family home. Always check the specific price ceiling for the grant or loan program you intend to use, as they rarely align with the total city market average.