Utah Mortgage Prequalification: Savvy Buyer’s Guide 2026

Showing up to a Salt Lake open house without a prequalification is the fastest way to lose your dream home to a cash buyer. With Salt Lake County median prices hitting $645,000 in 2026, the competition is fierce and the stakes are high. You probably feel that familiar knot of anxiety about whether you can actually afford the mortgage or if a lender will turn you down. Securing a utah mortgage prequalification for home buyers isn’t just about the numbers; it’s about gaining the confidence to strike when you find the right place in Lehi or Salt Lake.
We agree that the housing market feels like a high-stakes game where the rules are constantly changing. That’s why we’re showing you how to lock in a clear budget and unlock up to $5,000 in buyer rebates at closing. This guide breaks down the latest 2026 credit requirements, explains how to get a no-obligation letter through True North Mortgage, and reveals the strategies savvy buyers use to beat out the competition. You’ll finish this article with a clear plan to save money and a roadmap to getting your offer accepted without the stress.
Key Takeaways
- Learn why sellers in Lehi and Draper won’t let you tour a home without a preliminary evaluation of your creditworthiness.
- Identify the specific credit, income, and debt benchmarks required to qualify for the best financing in the 2026 market.
- Follow our 5-step roadmap to secure a utah mortgage prequalification for home buyers with zero cost or obligation.
- Distinguish between a quick look prequalification and a deep dive pre-approval to ensure your offer stands up to scrutiny.
- Unlock a buyer rebate of up to $5,000 at closing by strategically aligning your mortgage and realty services from the start.
Why Utah Home Buyers Need Prequalification First
Trying to buy a home without a mortgage pre-qualification is like trying to enter a high-stakes poker game without showing your buy-in. You aren’t getting a seat at the table. A utah mortgage prequalification for home buyers is a preliminary evaluation of your creditworthiness. It’s a quick financial snapshot that tells you exactly how much buying power you have. Without it, you’re just guessing; in this market, guessing is expensive.
In competitive pockets like Lehi or Draper, sellers have zero patience for uncertainty. Most listing agents won’t even unlock the front door for a tour unless you have a letter in hand. Presenting a prequalification from True North Mortgage instantly changes the temperature of the room. You stop being a random inquiry and start being a serious buyer. This isn’t just about ego. It’s about budget protection. Why spend your Saturdays touring luxury builds in Salt Lake County only to find out the bank won’t clear the check? Get the hard truth about your budget early so you can focus on homes you can actually win.
The Competitive Edge in the Wasatch Front
Markets like Saratoga Springs and Eagle Mountain are notoriously fast. If you wait until you find “the one” to start your paperwork, you’re already too late. Prequalification gives you the ability to strike immediately. It allows you to navigate multiple-offer situations with the confidence of a cash buyer. Sellers want the path of least resistance. When they see you’ve already cleared the first hurdle with a reputable lender, your offer moves to the top of the pile. It’s a psychological advantage that tells the seller you are prepared and capable.
Prequalification vs. Staying a “Window Shopper”
Scrolling through Zillow is a hobby; getting prequalified is a business decision. Realtors in Utah are busy. They prioritize buyers who are ready to sign, not those who are just testing the waters. Moving from a window shopper to a verified buyer is also your first step toward claiming the Utah home buyer rebate. Pay It Forward Realty LLC focuses on empowering serious buyers, and you can’t secure that $5,000 credit at closing if you’re still stuck in the browsing phase. Start the process now to ensure you’re positioned to save as much as possible on your new home.
The Financial “Big Three”: Credit, Income, and Debt
You want the house. The lender wants to know you can pay for it. Securing a utah mortgage prequalification for home buyers requires a deep look at three specific pillars: your credit score, your income history, and your debt-to-income (DTI) ratio. Think of these as your financial vitals. If one is weak, the whole deal could flatline. In a market where Salt Lake County homes average $645,000, your numbers need to be sharp before you start making offers.
Credit Score Benchmarks for Utah Loans
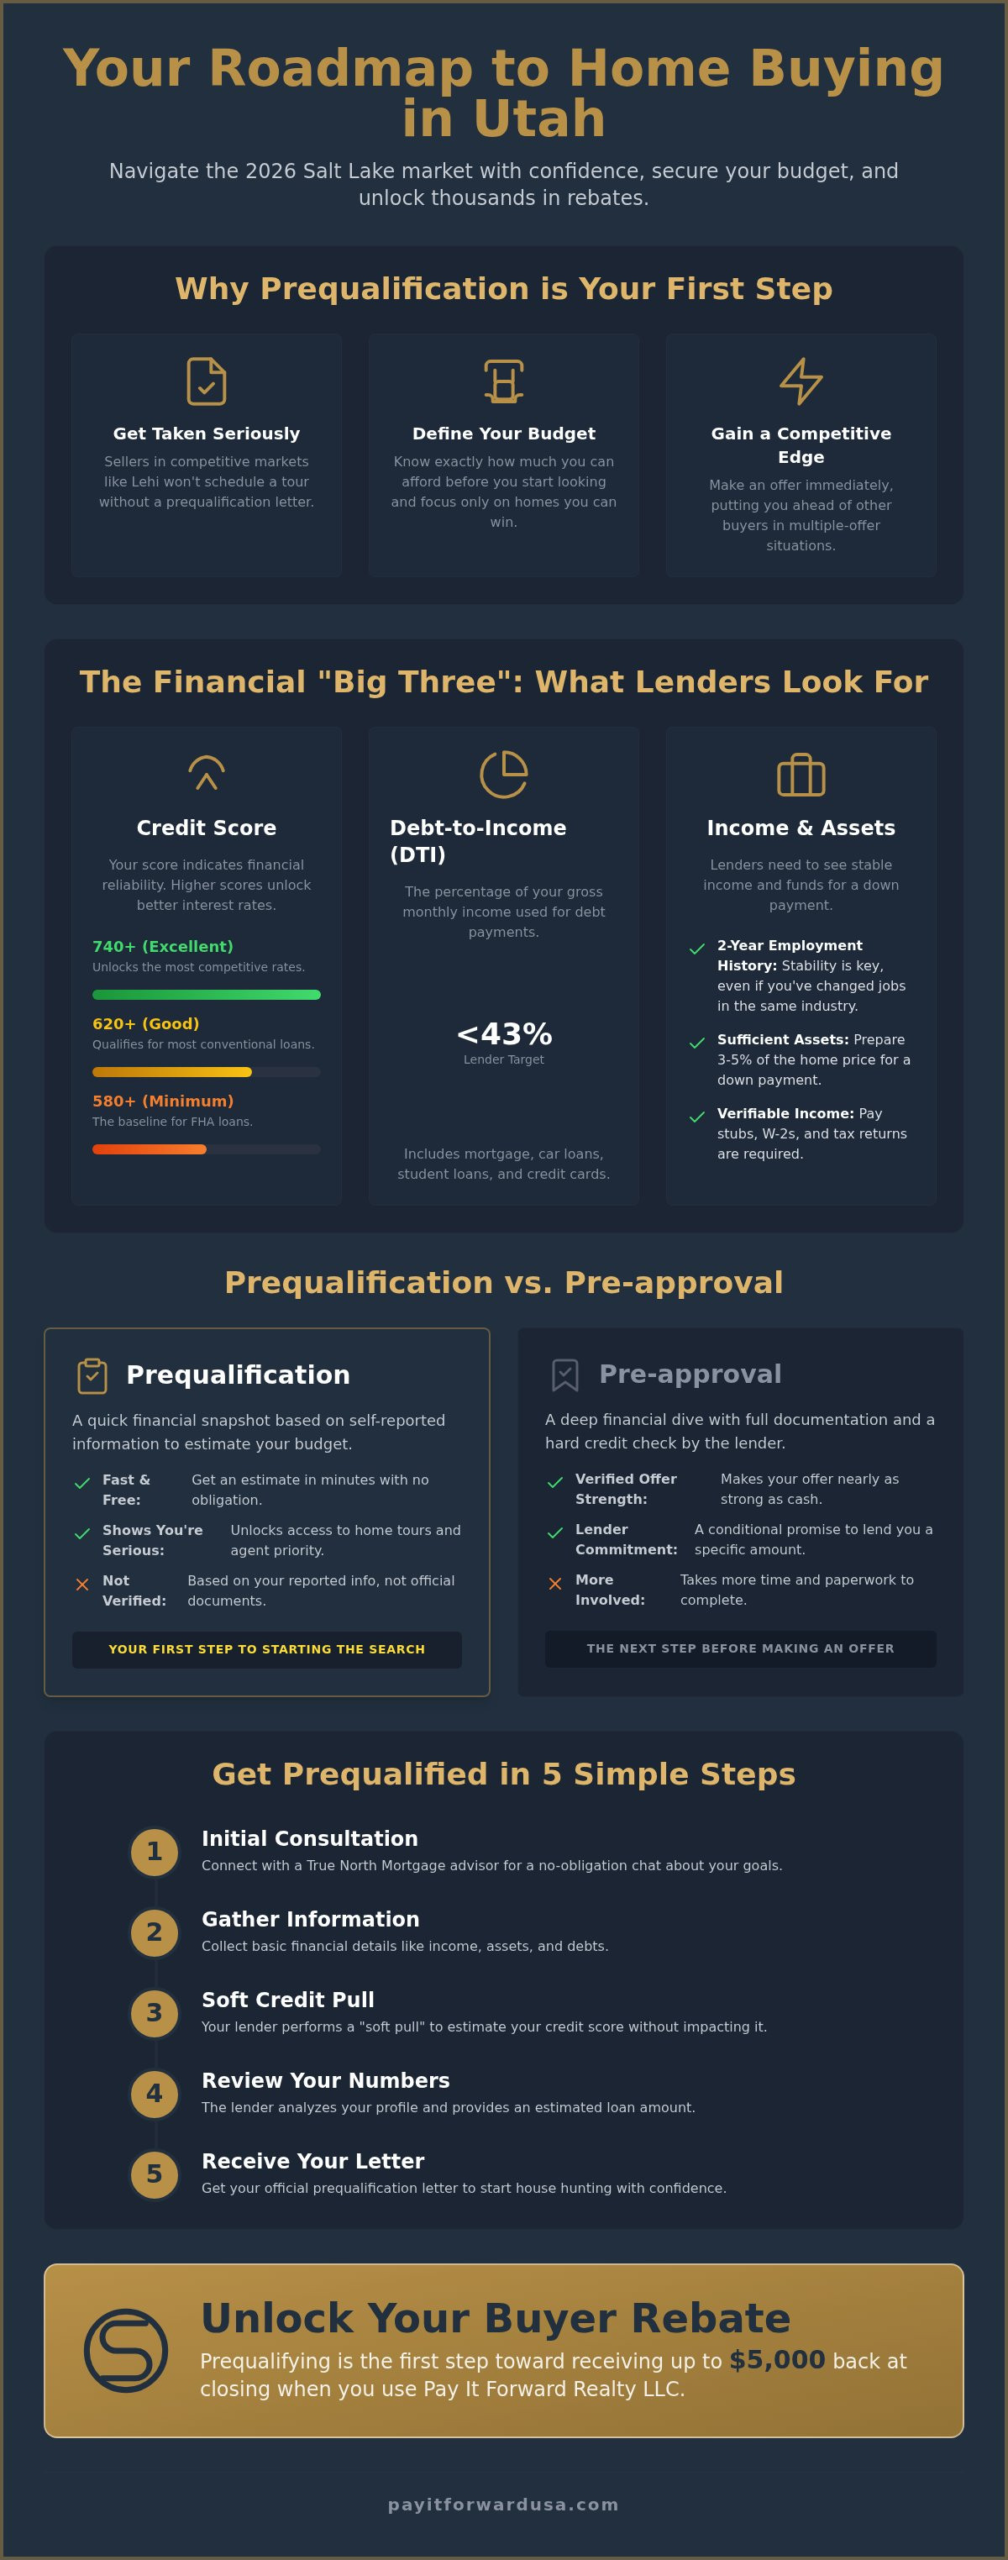
Your credit score is the first thing a lender checks. While you can often secure an FHA loan with a score as low as 580 (paired with a 3.5% down payment), most conventional lenders in Utah want to see at least a 620. Don’t settle for the minimum. Aim for 740 or higher to unlock the most competitive interest rates. Following FDIC guidance on mortgages, understanding how lenders weigh your credit history is essential for a smooth approval. Before the lender pulls a full report, use these quick tips:
- Request a “soft pull”: This allows you to see your estimated score without hurting your credit.
- Check for errors: Dispute any inaccuracies on your report at least three months before you buy.
- Avoid new debt: Don’t open new credit cards or buy a car while you’re in the prequalification phase.
Understanding Your Debt-to-Income Ratio
Your DTI is the “magic number” that determines your loan limit. It’s the percentage of your gross monthly income that goes toward paying debts. Most lenders prefer a DTI below 43%. If you earn $10,000 a month, your total debt payments (including your future mortgage, taxes, and insurance) shouldn’t exceed $4,300. Student loans and car payments are the biggest DTI killers in the Wasatch Front. Paying down high-interest credit cards before you apply frees up more buying power for your home purchase.
Lenders also look for income stability, usually requiring a two-year employment history. If you’ve recently moved from a tech role in Lehi to a new firm in Salt Lake, don’t worry. As long as you’ve stayed in the same industry, you’re usually fine. If you’re ready to see where your numbers land, True North Mortgage can run a free analysis to help you prepare. Remember, you’ll also need to show assets for a down payment. In 2026, the conforming loan limit for most of Utah is $832,750, so having 3% to 5% ready for a conventional loan is a smart baseline.
Utah Mortgage Prequalification vs. Pre-approval
Don’t let the industry jargon confuse you. While they sound similar, prequalification and pre-approval serve two completely different purposes in your journey. A utah mortgage prequalification for home buyers is essentially a preliminary conversation. You tell the lender what you make and what you owe. They give you a ballpark figure. It’s fast. It’s easy. But it isn’t a guarantee. Pre-approval, on the other hand, is the financial heavy lifting. This is where the lender verifies every word you said with hard evidence. Understanding the difference between Prequalification vs. Pre-approval is often the difference between a rejected offer and a new set of keys.
The Prequalification Process
Think of prequalification as your scouting report. It’s perfect for the early stages when you’re exploring neighborhoods like Herriman or South Jordan. You can get it done almost instantly. It requires no formal documentation and usually relies on the data you provide. Best of all, it’s a no-obligation step that typically has no impact on your credit score. You get a clear budget range without the pressure of a formal application. Use this phase to narrow down your search and see what’s realistic for your monthly payment.
The Pre-approval Process
When you’re ready to stop browsing and start bidding, you need a pre-approval. This process involves a deep dive into your financial life. You’ll need to provide tax returns, pay stubs, and bank statements. The lender will also perform a hard credit check to see your actual score. Pre-approval is the formal commitment from a lender to provide a specific loan amount. This letter is your golden ticket when buying a home in Utah. Sellers won’t take your offer seriously without it because it proves a bank has already vetted your finances and is ready to fund the deal.
True North Mortgage offers both options to keep your home-buying journey flexible. You can start with a quick, free prequalification to test the waters. When the right house hits the market, you can quickly pivot to a full pre-approval. This strategic approach ensures you’re always prepared but never rushed. It also keeps you on track for that $5,000 buyer rebate. Why settle for one or the other when you can have a lender that adapts to your speed?
How to Get Prequalified in Utah: 5 Simple Steps
Stop overcomplicating the process. You don’t need a mountain of paperwork or a week of waiting to find out where you stand. Getting a utah mortgage prequalification for home buyers is surprisingly fast when you have the right partner. It’s the first real move toward homeownership. Follow these five steps to go from a dreamer to a documented buyer in less than a day.
- Step 1: Gather your vitals. You don’t need tax returns yet. Just have your annual gross income, current employer details, and a list of monthly debts like credit cards, car loans, and student loans ready.
- Step 2: Connect with a local expert. Reach out to True North Mortgage for a free consultation. They know the Utah market and can guide you through the nuances of local lending.
- Step 3: Submit your application. Do it online or over the phone. It’s a quick, high-level conversation about your financial health, not a deep-dive audit.
- Step 4: Review the numbers. Don’t just look at the total loan amount. Look at the estimated monthly payment including taxes and insurance. Does it actually fit your lifestyle?
- Step 5: Grab your letter. Once the data is processed, you’ll receive your official Utah mortgage prequalification letter. This is your ticket to tour homes and make offers.
What Information You’ll Need Ready
Speed is everything. To move fast, have your current employer’s contact info and your total gross income (before taxes) on hand. You’ll also need to disclose your monthly debt obligations. Lenders use these to calculate your DTI. If you’re looking in specific areas like Saratoga Springs or Lehi, mention those zip codes. Property taxes vary by county; including them in the estimate ensures your monthly payment calculation is accurate from day one.
Timeline: How Fast Can You Get It?
In the competitive Utah market, a letter that takes three days is useless. Most savvy buyers can secure their prequalification in under 24 hours. If you start on a Thursday, you can be touring homes by Friday afternoon. This speed is vital for the weekend rush when the best properties in Salt Lake County often see multiple offers by Sunday night. If interest rates or home prices shift, True North Mortgage can quickly update your letter to reflect your current buying power. This agility keeps you in the game when others are stuck waiting for a callback.
Ready to see what you can afford? Start your free prequalification today and get one step closer to your $5,000 buyer rebate.
The Secret Weapon: Prequalification + $5,000 Rebate
Most buyers view a utah mortgage prequalification for home buyers as a boring administrative hurdle. It is the paperwork you finish so you can finally go look at houses. But savvy buyers in Salt Lake and Lehi know better. Prequalification is actually the strategic trigger that unlocks a massive financial advantage. By partnering with True North Mortgage and Pay It Forward Realty LLC, you aren’t just getting a loan. You’re positioning yourself for a $5,000 windfall at the closing table.
The synergy between these two partners is where the magic happens. True North Mortgage handles the lending side with a free, no-obligation utah mortgage prequalification for home buyers. Pay It Forward Realty LLC then manages the purchase side of the transaction. Because these teams work in tandem, they’ve stripped away the traditional industry waste. Instead of that money going toward corporate overhead or outdated marketing budgets, it goes back to you. It’s a bold, transparent alternative to the status quo that prioritizes your bottom line over industry tradition.
Unlocking the Buyer Rebate
The rebate is your reward for being a prepared, smart buyer. When you show up with a prequalification letter in hand, you’ve already done the heavy lifting. You’ve proven you’re ready to act. This efficiency allows us to offer a rebate of up to $5,000. Think about what that cash does for your transition. You can use it to cover closing costs, buy down your interest rate, or pay for moving expenses to your new place in Herriman or South Jordan. This is a core part of our low commission real estate Utah model. We believe you should keep more of your equity, whether you’re selling or buying.
Next Steps: Get Started Today
Ready to move from being a prequalified lead to a “homeowner with a check”? The path is clear and direct. Don’t wait for the market to get even more competitive. Take these final steps to secure your future:
- Start your prequalification: Contact True North Mortgage for your free, no-obligation financial snapshot.
- Schedule a consult: Talk with Principal Broker Kurt Mathewson about how the rebate works for your specific budget and target area.
- Launch your search: Use your new letter to start touring homes in Lehi, Orem, or Provo with total confidence.
Stop dreaming about a new home and start making moves that matter. You have the tools. You have the roadmap. Now, take the lead and claim the $5,000 rebate you deserve. Your future self will thank you for being the smartest buyer in the room. This isn’t just about finding a house; it’s about winning the transaction.
Lock in Your Budget and Claim Your Rebate
You now have the strategic blueprint to dominate the 2026 housing market. You understand that a utah mortgage prequalification for home buyers is your ticket to being taken seriously in Lehi, Salt Lake, and across the Wasatch Front. By mastering your credit score and debt-to-income ratio, you’ve removed the anxiety of the unknown. You’re no longer just browsing; you’re preparing to win. Most importantly, you know that this preparation is the key to unlocking a $5,000 buyer rebate at closing.
Don’t let another weekend pass without knowing your true buying power. True North Mortgage offers a free, no-obligation analysis to get you moving. It’s fast. It’s simple. It’s the smartest move you’ll make this year. Get Your Free Utah Mortgage Prequalification Now! and claim the financial advantage you deserve. You’ve done the research. You’ve got the plan. Now, go get your keys. We’re ready when you are.
Frequently Asked Questions
Is mortgage prequalification the same as pre-approval in Utah?
No, they serve different purposes. Prequalification is a basic estimate based on unverified data you provide to the lender. Pre-approval is a formal commitment that requires hard verification of tax returns, bank statements, and pay stubs. While utah mortgage prequalification for home buyers helps you set an initial budget, serious sellers in Salt Lake County usually demand a full pre-approval letter before they will accept your final offer.
Does a mortgage prequalification affect my credit score?
Usually not. Most lenders perform a soft pull for a prequalification, which doesn’t impact your credit score at all. This allows you to explore your financial options without penalty. However, once you move to the formal pre-approval phase, the lender will conduct a hard pull that can cause a temporary, minor dip in your score. Always ask your lender which type of credit check they use first.
How long does a Utah mortgage prequalification letter last?
Most letters are valid for 60 to 90 days. This timeframe accounts for potential shifts in your financial situation or market interest rates. If your search in cities like Lehi or Draper takes longer than expected, don’t worry. You can typically refresh your letter with a quick phone call to your lender. They will just need to confirm that your income, debt levels, and credit score haven’t changed.
Can I get prequalified if I am self-employed in Utah?
Yes, but you should expect to provide more documentation than a standard W-2 employee. Lenders typically want to see at least two years of consistent business income through tax returns and profit and loss statements. Because self-employed income can fluctuate, starting a utah mortgage prequalification for home buyers early is smart. It gives you time to ensure your reported net income meets the requirements for the specific loan amount you want.
What is the minimum credit score for Utah home buyers in 2026?
The floor is generally 580 for FHA loans with a 3.5% down payment. If you’re aiming for a conventional loan, most Utah lenders require at least a 620. Keep in mind that these are just minimums. To secure the most competitive interest rates in 2026, you should aim for a score of 740 or higher. Higher scores give you more leverage and can save you thousands over the life of the loan.
Do I have to pay a fee for mortgage prequalification?
No, you should never pay for a standard prequalification. True North Mortgage provides this service for free with no obligation to use them for your final loan. It’s a tool designed to empower you, not a product to be sold. If a lender asks for an upfront fee just to give you a preliminary budget estimate, consider it a red flag and look for a more transparent partner.
How much can I actually save with the Pay It Forward buyer rebate?
You can save up to $5,000 at closing. This isn’t a discount on the home price; it’s actual cash back or a credit toward your closing costs. By using our streamlined model, we pass the savings directly to you. This rebate can be used for anything from moving expenses to home upgrades. It turns a standard Utah home purchase into a significant financial win for your household budget.
Can I use a prequalification from an out-of-state lender in Utah?
You can, but it might put you at a disadvantage. Utah listing agents often prefer letters from local lenders who understand state-specific taxes, insurance norms, and closing timelines. A letter from a local expert like True North Mortgage carries more weight in a multiple-offer situation. It signals to the seller that your financing is handled by someone who knows the nuances of the competitive Wasatch Front market.