Utah First Time Home Buyer Rebate: Get Up to $5,000 Cash Back in 2026

Why are most first-time buyer programs in Utah forcing you into a brand-new house you might not even want? It’s a fair question. You’ve likely spent months watching interest rates climb and seeing your down payment savings stretch thinner while searching for a utah first time home buyer rebate that actually works. It feels like every “grant” you find is actually a deferred loan with a mountain of strings attached. You want a home that fits your life, not just a property that fits a government checklist.
We get it. The confusion between loans, grants, and rebates is enough to make anyone’s head spin. That’s why you need a smarter path. In this guide, you’ll discover how to secure a buyer rebate of up to $5,000 to slash your out-of-pocket closing costs on any home in the state. Whether you’re eyeing a charming bungalow in Salt Lake City or a family home in Saratoga Springs, this cash back puts the power back in your hands.
We’re pulling back the curtain on how savvy buyers are skipping restrictive state programs and getting paid to buy the home they actually want. It’s time to stop leaving money on the table and start your homeownership journey with a local ally who prioritizes your bottom line.
Key Takeaways
- Define the rebate as a legal commission split that slashes your out-of-pocket expenses at the closing table.
- See why a utah first time home buyer rebate offers more flexibility than state programs that restrict you to new builds or specific price caps.
- Discover how to use up to $5,000 in cash back to permanently buy down your interest rate or cover essential closing costs.
- Learn the exact steps to partner with a local advocate and secure your rebate on almost any residential home listed in Utah.
What Exactly is a Utah First Time Home Buyer Rebate?
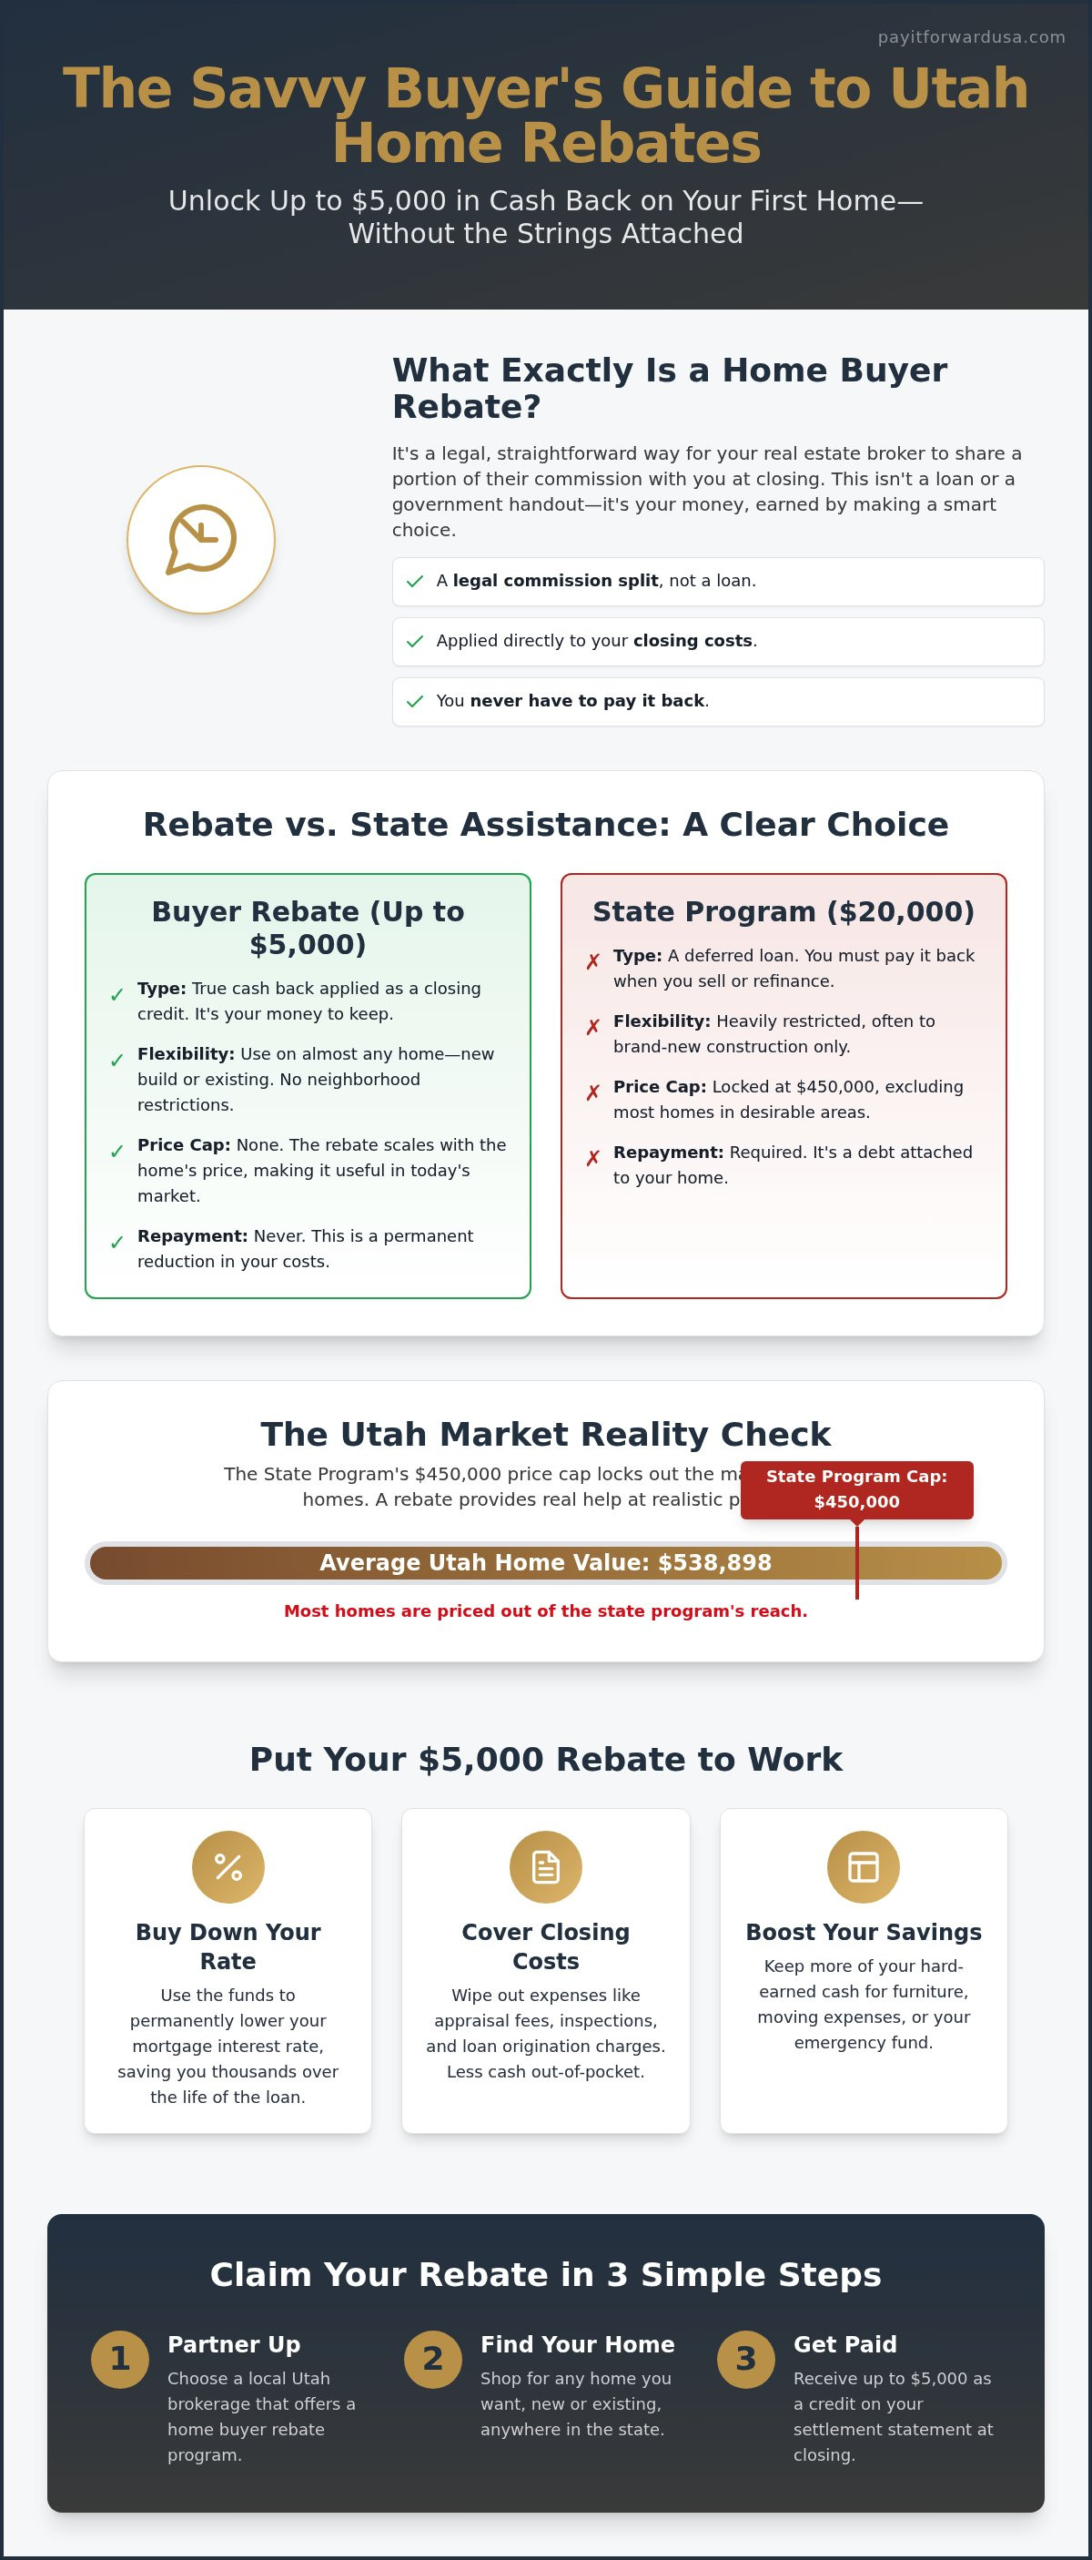
Stop thinking of real estate commissions as a fixed, untouchable cost. Most buyers assume the money paid to agents is just part of an unchangeable “system.” It isn’t. A utah first time home buyer rebate is a legal commission-sharing agreement between you and your real estate broker. Essentially, when a seller pays a commission to the agents involved in the deal, your broker takes a portion of that money and hands it back to you at the finish line.
Is it legal? Absolutely. Utah is one of the states where commission rebates are fully permitted and even encouraged by consumer advocacy groups. While some traditional agents might keep the full amount for themselves, a savvy buyer knows that modern brokerages are willing to share. This isn’t a “discount” service; it’s a transparency-first model that rewards you for being an informed participant in the transaction. Unlike state assistance programs, this money is yours to keep. You don’t have to pay it back when you sell or refinance your home later.
How Rebates Differ from Government Grants
Government programs often feel like a maze of red tape. In 2026, many Utah state programs are actually structured as deferred loans, not grants. They come with “strings” like strict income caps, 12-month residency requirements, or limits to brand-new construction only. A utah first time home buyer rebate is different. It’s based on the purchase price of the home, not your tax return or your job history. In a market where the average Utah home value sits well above $530,000, these rebates provide a flexible financial cushion that government programs simply can’t match. You aren’t restricted to specific neighborhoods or “new build only” properties. You get the freedom to choose an existing home in an established area without sacrificing your financial edge.
Is it Cash in Hand or a Closing Credit?
Most lenders prefer the rebate to appear as a credit on your settlement statement. This is great news for your bank account. Instead of waiting for a check in the mail after you move in, the money is applied directly to your closing costs. Think about the immediate impact. A $5,000 credit can wipe out your inspection fees, appraisal costs, and loan origination charges in one fell swoop. This isn’t just a minor discount. It is a massive reduction in the actual “cash to close” you need to provide on signing day.
- Covers professional home inspections and radon testing.
- Offsets the cost of a required real estate broker and lender-mandated appraisal.
- Reduces the total liquid cash you need to bring to the table.
By lowering your out-of-pocket expenses, you keep more of your hard-earned savings for things like new furniture, appliances, or emergency repairs. It’s an immediate win that makes the high-stakes Utah market feel a lot more manageable for any first-time buyer.
Rebates vs. the $20,000 State Assistance Program
Don’t let the big numbers on a billboard fool you. While the state’s highly publicized First-time Homebuyer Assistance Program sounds like a massive win, it comes with heavy restrictions that might not fit your life. For many, a utah first time home buyer rebate is the smarter, more flexible move. Why? Because the state program isn’t a gift; it’s a loan. It is a debt you carry until you sell or refinance. In contrast, a buyer rebate is your money from day one. It’s a direct reduction in your costs that you never have to pay back. It’s your equity, not the government’s.
The state assistance is also currently capped at a $450,000 purchase price. That’s a serious problem in today’s market. With the average Utah home value sitting near $538,898, finding a home under that $450k ceiling in hotspots like Lehi or Draper is nearly impossible. If your dream home costs more, you’re locked out of state funds. A utah first time home buyer rebate doesn’t have those arbitrary ceilings. It scales with your purchase price, providing a realistic tool for the actual Utah market of 2026. You can even combine a rebate with other seller concessions if you structure the deal correctly. Want to see how much you could save? You can check your potential rebate amount here before you even start touring homes.
The ‘New Construction’ Trap
Limiting your search to new builds just to get state money might be a costly mistake. New construction often carries a premium price tag and might be located far from your work or preferred schools. Existing homes in Salt Lake City or Orem frequently offer more value per square foot and established neighborhoods. When you use a commission rebate, you aren’t forced into a specific type of inventory. You can buy that charming 1950s rambler or a sleek modern condo and still get up to $5,000 back at closing. It turns any home on the MLS into a deal.
Repayment Terms: The Fine Print You Need to Know
The fine print on state programs is where the “free money” illusion fades. Many state-funded options require you to repay the full amount, or even a percentage of your equity, the moment you refinance or sell. This effectively eats into your future wealth. A commission rebate has zero repayment requirements. It is simply a portion of the agent’s commission that is legally shared with you. By preserving your equity from the start, you’re building long-term wealth in Utah real estate instead of just managing a government loan.
Maximizing Your Savings in the Utah Market
Smart buyers don’t just take the cash and run. They use it as a strategic weapon. In 2026, understanding the full range of Utah home buying incentives is about more than just finding a discount. It is about leverage. A utah first time home buyer rebate can be the deciding factor between a high monthly payment and a manageable one. Instead of just letting that $5,000 sit in your bank account, you can use it to “buy down” your interest rate permanently. This move slashes your monthly obligation for the entire life of the loan. It’s a long-term play that pays dividends every single month.
You can also stack your rebate with seller concessions. If you negotiate for the seller to cover 3% of your closing costs, your commission rebate adds another $5,000 on top of that. This combination creates a “zero-down” feel by keeping your liquid savings untouched. In a market where the typical down payment for first-time buyers is around 9%, every dollar you keep in your pocket matters. It gives you the financial breathing room to handle the transition into homeownership without draining your emergency fund.
Winning Bids in Silicon Slopes
Competition is fierce in Lehi, Eagle Mountain, and American Fork. Sellers in these hubs prioritize speed and certainty. To win here, you need to be prequalified through local partners like True North Mortgage before you ever step foot in an open house. This shows sellers you have the backing to close the deal. Your utah first time home buyer rebate then acts as a safety net. If an appraisal comes in slightly lower than your offer price in a bidding war, that $5,000 credit can help cover the gap. It gives you the confidence to negotiate from a position of strength.
Covering the ‘Hidden’ Costs of Buying
The purchase price is only one part of the equation. Closing day often brings a wave of “hidden” expenses that catch buyers off guard. Use your rebate to wipe these out. In high-end markets like Draper or Alpine, a high-tech home inspection or a specialized radon test can cost hundreds. Your rebate can also pay for a one-year home warranty, protecting you from expensive repairs during your first months in the house. As property taxes continue to shift across the state, having that extra $5,000 credit at the settlement table reduces the sting of these mandatory upfront costs.
Eligibility: Who Can Claim a Utah Home Buyer Rebate?
You don’t need a golden ticket or a perfect tax return to qualify for these savings. Unlike state-sponsored loans that grill you on your debt-to-income ratio and household size, a utah first time home buyer rebate has zero income restrictions. It doesn’t matter if you’re buying a modest starter condo or a sprawling luxury estate in Sandy. The eligibility is refreshingly simple. You just need to sign a buyer broker agreement with Pay It Forward Realty before you start making offers. This agreement is the legal engine that allows us to share the commission with you at the closing table.
The rebate amount is calculated based on the final sales price of the home and the commission offered by the seller’s side. It applies to almost any residential property you can find on the market today. If it’s a house, townhome, or condo within the state of Utah, it likely qualifies. This transparency removes the barriers that usually keep buyers in the dark about where the commission money actually goes. It’s about professional expertise meeting common-sense savings without the government oversight.
Does it Have to be Your First Home?
Here’s the best part. While we often focus on the utah first time home buyer rebate because those buyers are hit hardest by high interest rates, you don’t actually have to be a first-timer to win. This is an “any-time” benefit for savvy consumers. If you’re a repeat buyer looking to upgrade to a bigger yard in Lehi or downsize to a low-maintenance spot in Draper, you’re still eligible. State grants are often one-and-done deals with strict clocks and repayment “traps.” Rebates are a permanent tool for homeowners who want to slash their costs on every transaction they make. Ready to lock in your savings? You can start your buyer agreement online right now to ensure you don’t leave money on the table.
The MLS Requirement
To make the commission structure work, the property generally needs to be listed on the Utah Multiple Listing Service (MLS). This is where the seller’s agent publicly declares the commission they are willing to pay to the buyer’s broker. What if you find a “For Sale By Owner” (FSBO) property? Don’t panic. We can still handle FSBO deals with a rebate agent, though it requires a bit of extra negotiation with the seller to ensure the commission is properly accounted for in the settlement. Our agents are active members of the local Utah real estate boards, ensuring we have the visibility and legal standing to access those funds on your behalf. We pull back the curtain on the industry to put those funds back in your pocket.
How to Claim Your $5,000: The 3-Step Process
You shouldn’t need a PhD in finance to get your own money back. We’ve stripped away the corporate fluff to create a process that’s scrappy, efficient, and built for the 2026 market. Securing your utah first time home buyer rebate isn’t a mystery. It is a straight line from your first click to your final signature. While other buyers are busy filling out endless government forms, you’ll be moving through a streamlined system designed to put up to $5,000 back in your pocket. It’s about working smarter, not harder, to keep your equity where it belongs.
Step 1: The Financial Foundation
Skipping prequalification is the single biggest mistake you can make in the Beehive State. In a competitive market, an offer without a prequalification letter is just a piece of paper. We’ve partnered with True North Mortgage to make this step painless. It is a free, no-obligation process that sets your actual budget so you don’t waste time touring homes you can’t afford. This foundation is crucial for your success. You can dive deeper into the logistics with our buying a home in Utah guide to see how low-commission models are changing the game. Get your numbers right first, and the rest of the search becomes a lot less stressful.
Step 2 & 3: From Search to Savings
Once you’re prequalified, you partner with Pay It Forward Realty as your exclusive buyer’s agent. This is where the fun begins. We help you navigate the inventory in high-demand areas like West Jordan, Bountiful, and South Salt Lake. You aren’t limited to specific neighborhoods or restrictive builders. Principal Broker Kurt Mathewson oversees the brokerage operations to ensure your utah first time home buyer rebate is structured correctly in your buyer broker agreement. This professional oversight means you don’t have to worry about the legal technicalities. We handle the paperwork; you focus on finding the right kitchen and the perfect backyard.
The magic happens on closing day. You won’t be waiting for a check in the mail weeks after you move in. Instead, look at your final closing disclosure. You will see a direct credit of up to $5,000 applied to your settlement. This credit slashes the total amount of liquid cash you need to bring to the table. It is a visible, tangible result of being a savvy buyer. You walk away with the keys to your new home and thousands of dollars in savings that would have otherwise gone into an agent’s pocket. It’s a clean, decisive victory for your bank account.
Take Control of Your Home Purchase Today
The path to homeownership in Utah shouldn’t be a financial trap. You now know that a utah first time home buyer rebate offers the freedom state-funded loans simply can’t match. By choosing a rebate, you skip the repayable debt and the “new-build only” restrictions. You get up to $5,000 back at closing on any home that actually fits your life. This is the smartest way to protect your equity from the very first signature.
Don’t leave your hard-earned money on the table. With free mortgage prequalification through True North Mortgage and expert guidance from Principal Broker Kurt Mathewson, you have a bold ally in your corner. It is time to stop following the status quo and start buying with intelligence. Claim Your $5,000 Utah Home Buyer Rebate Today and watch your closing costs drop at the settlement table. You’ve got the tools and the strategy; now it’s time to make your move. You’ve got this.
Frequently Asked Questions
Is a real estate commission rebate legal in Utah?
Yes, commission rebates are 100% legal in Utah. The state allows real estate brokers to share their earned commission with buyers as a financial incentive. This practice is even supported by the U.S. Department of Justice because it fosters competition and lowers costs for consumers. You’re simply entering a legal agreement with your broker to receive a portion of the fee paid by the seller. It’s a transparent way to make homeownership more affordable.
Can I use the $5,000 rebate for my down payment?
Lenders typically require your utah first time home buyer rebate to be applied toward closing costs rather than the actual down payment. Most loan programs like FHA or Conventional have strict rules about the source of your down payment funds. However, when the rebate covers your inspections, appraisals, and lender fees, you keep more of your own liquid cash. This effectively makes your total out-of-pocket expense much lower on signing day.
Do I have to pay taxes on my home buyer rebate?
In most cases, you don’t pay income tax on a commission rebate. The IRS generally treats these funds as a reduction in the purchase price of your home; they aren’t taxable income. This means the rebate lowers your “cost basis” in the property. While you should always verify your specific situation with a qualified tax professional, most buyers enjoy this benefit without worrying about a surprise bill from the IRS at the end of the year.
Will my lender allow me to receive a commission rebate?
Most lenders will absolutely allow a commission rebate as long as it’s disclosed early in the process. The credit must appear clearly on your final Closing Disclosure. We work closely with partners like True North Mortgage who are experts at handling these specific transactions. Transparency is key here. By showing the lender exactly where the funds are coming from, you ensure a smooth approval process without any last-minute hurdles at the settlement table.
Does the rebate apply to new construction homes in Lehi?
Yes, the utah first time home buyer rebate applies to new construction in Lehi, Saratoga Springs, or anywhere else in Utah. If a builder offers a commission to buyer’s agents, we can share that with you. This is a huge advantage because you can often combine our rebate with builder-specific incentives like upgraded appliances. It turns a standard new-build purchase into a much better financial deal without the typical state-loan restrictions.
What happens if the commission offered by the seller is less than 3%?
Your rebate is calculated as a portion of the actual commission paid by the seller. If the offered commission is lower than the standard 3%, the rebate amount scales proportionally up to $5,000. We are always upfront about these numbers before you sign an offer. Our goal is to maximize your savings regardless of the specific commission structure. You’ll always know exactly what to expect on your settlement statement before you close.
How does Pay It Forward Realty offer this when other brokers don’t?
We choose to operate differently than traditional franchises. By cutting out expensive office leases and national franchise fees, we keep our overhead low. This scrappy and efficient model allows us to pass the savings directly to you. Principal Broker Kurt Mathewson believes in transparency and consumer advocacy. We don’t think a broker should keep every penny of a commission when we can help our clients succeed in a tough, high-stakes marketplace.